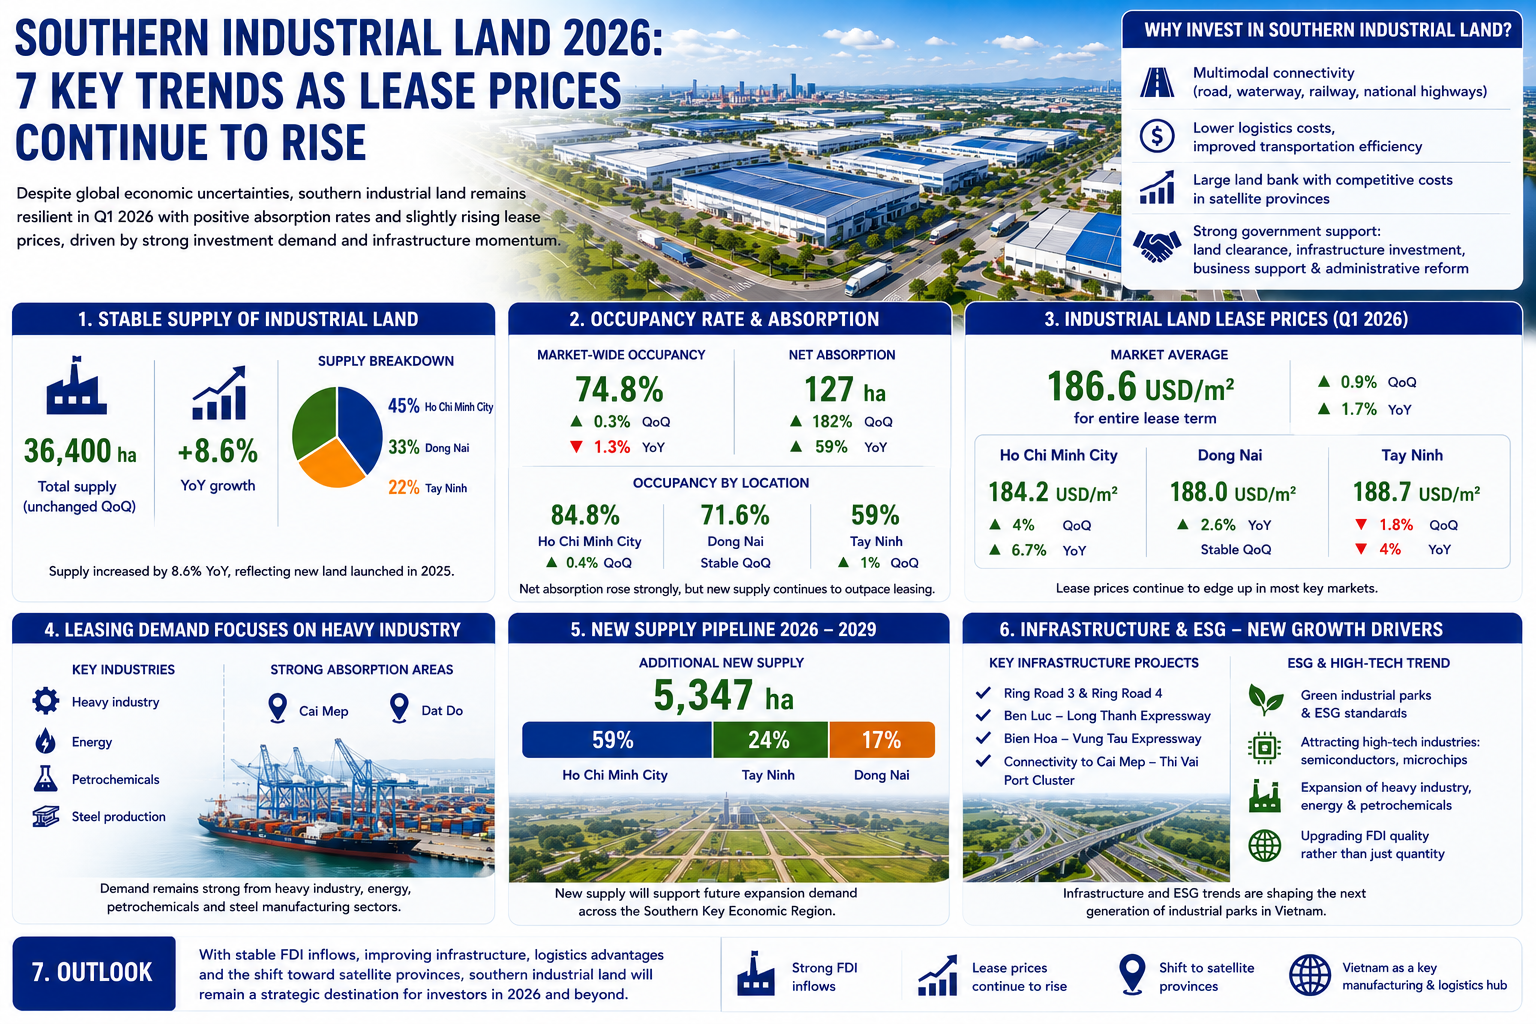
Southern industrial land continues to show strong resilience in 2026 despite ongoing global economic uncertainties. Recent market data indicates that this segment maintains positive absorption rates, steady lease price growth, and sustained investor interest in strategically located industrial zones. This confirms that industrial real estate in Southern Vietnam remains one of the market’s brightest sectors.
As Vietnam continues strengthening its position in global supply chains, industrial land in the Southern Key Economic Region is expected to enter a new growth cycle between 2026 and 2029.
Southern Industrial Land Supply Remains Stable
According to market data, the total supply of southern industrial land currently stands at approximately 36,400 hectares, largely unchanged from the previous quarter due to the absence of new supply launches.
However, compared with the same period last year:
- supply increased by approximately 8.6%
- reflecting substantial new land introduced during 2025
Current supply distribution:
- Ho Chi Minh City accounts for approximately 45%
- Dong Nai accounts for 33%
- Tay Ninh accounts for 22%
This suggests the market is entering an absorption phase rather than aggressively expanding supply.
Industrial Land Occupancy Continues to Improve
Stronger Absorption Momentum
In Q1 2026:
- market-wide occupancy reached 74.8%
- increased 0.3% quarter-over-quarter
- declined 1.3% year-over-year
Net absorption reached:
- approximately 127 hectares
- up 182% quarter-over-quarter
- up 59% year-over-year
Although absorption accelerated significantly, overall occupancy has not surged due to new supply continuing to outpace leasing demand.
Compared with Q1 2025:
- the market expanded by approximately 2,871 hectares
- leased industrial land increased by around 1,710 hectares
Ho Chi Minh City Leads Occupancy Rates
By location:
Ho Chi Minh City
- occupancy rate: 84.8%
- up 0.4% quarter-over-quarter
Key drivers:
- strong demand from high-value manufacturing industries
- strategic location advantages
- mature logistics infrastructure
Dong Nai
- stable at 71.6%
Tay Ninh
- improved to 59%
- recovering from a lower base
7 Key Trends in Southern Industrial Land
1. Industrial Land Lease Prices Continue Rising
Average industrial land asking price in Q1 2026:
- approximately USD 186.6/m²
- for the full lease term
- up 0.9% quarter-over-quarter
- up 1.7% year-over-year
This reflects continued healthy demand.
2. Ho Chi Minh City Remains a Premium Market
Lease prices in Ho Chi Minh City:
- approximately USD 184.2/m²
- up 4% quarter-over-quarter
- up 6.7% year-over-year
Growth drivers:
- limited land availability
- strong demand
- strategic central positioning
3. Dong Nai Maintains Pricing Stability
Dong Nai industrial land remains stable at:
- approximately USD 188/m²
- up slightly 2.6% year-over-year
This highlights Dong Nai’s attractiveness thanks to:
- Long Thanh International Airport
- regional expressways
- strong logistics advantages
4. Tay Ninh Faces Competitive Pricing Pressure
Tay Ninh recorded:
- approximately USD 188.7/m²
- down 1.8% quarter-over-quarter
- down 4% year-over-year
Reasons include:
- large supply pipeline
- relatively high vacancy
- stronger market competition
5. Investment Shifts Toward Satellite Provinces
A clear trend is the movement of industrial investment toward satellite provinces.
Reasons include:
- larger land reserves
- more competitive costs
- suitability for large-scale manufacturing
Beneficiary locations include:
- Dong Nai
- Tay Ninh
- Ba Ria – Vung Tau
- Long An
6. Infrastructure Becomes a New Price Growth Catalyst
Major infrastructure projects creating momentum include:
- Ring Road 3
- Ring Road 4
- Ben Luc – Long Thanh Expressway
- Bien Hoa – Vung Tau Expressway
- Cai Mep – Thi Vai port connectivity
These developments are forming new industrial corridors.
7. ESG and High-Tech Manufacturing Shape Future Demand
New-generation industrial parks are increasingly prioritizing:
- ESG standards
- green industrial parks
- high-tech manufacturing
- semiconductor production
- microchip manufacturing
- advanced logistics
This reflects a clear shift toward higher-quality FDI.
Leasing Demand Concentrates in Heavy Industry
Current leasing demand remains focused on:
- heavy industry
- energy
- petrochemicals
- steel manufacturing
Strong absorption areas include:
- Cai Mep
- Dat Do
These locations benefit from powerful logistics infrastructure.
Southern Industrial Land Supply Through 2029
Forecast for 2026–2029:
- approximately 5,347 hectares of new supply
Supply distribution:
- Ho Chi Minh City: 59%
- Tay Ninh: 24%
- Dong Nai: 17%
This pipeline should help meet future expansion demand.
Outlook for Southern Industrial Real Estate
The market continues benefiting from:
- stable FDI inflows
- accelerating infrastructure development
- stronger regional logistics
- global supply chain relocation
- rising high-tech manufacturing demand
These factors support continued momentum for southern industrial land.
Conclusion
Southern industrial land remains one of Vietnam’s most resilient and attractive real estate segments in 2026.
Despite global uncertainties, leasing demand remains healthy, prices continue rising, and new industrial corridors are emerging.
Over the medium and long term, Southern Vietnam will continue to be a strategic destination for industrial investors, logistics operators, and industrial real estate developers.
References:
Free access to exclusive information on warehouse, factory, and land rentals in Dong Nai, Binh Duong, Long An, Ho Chi Minh City, and more.
KHU CÔNG NGHIỆP 247 is a company operating in the field of buying, selling, and leasing factories and real estate.. We are proud to be a leading provider of real estate services in Vietnam. We have a team of highly qualified and experienced real estate consultants who always place trust and credibility at the core of everything we do.
Phone: 0901 490 348
Email: datkhucongnghiep247@gmail.com
Website: datkhucongnghiep247.com.vn