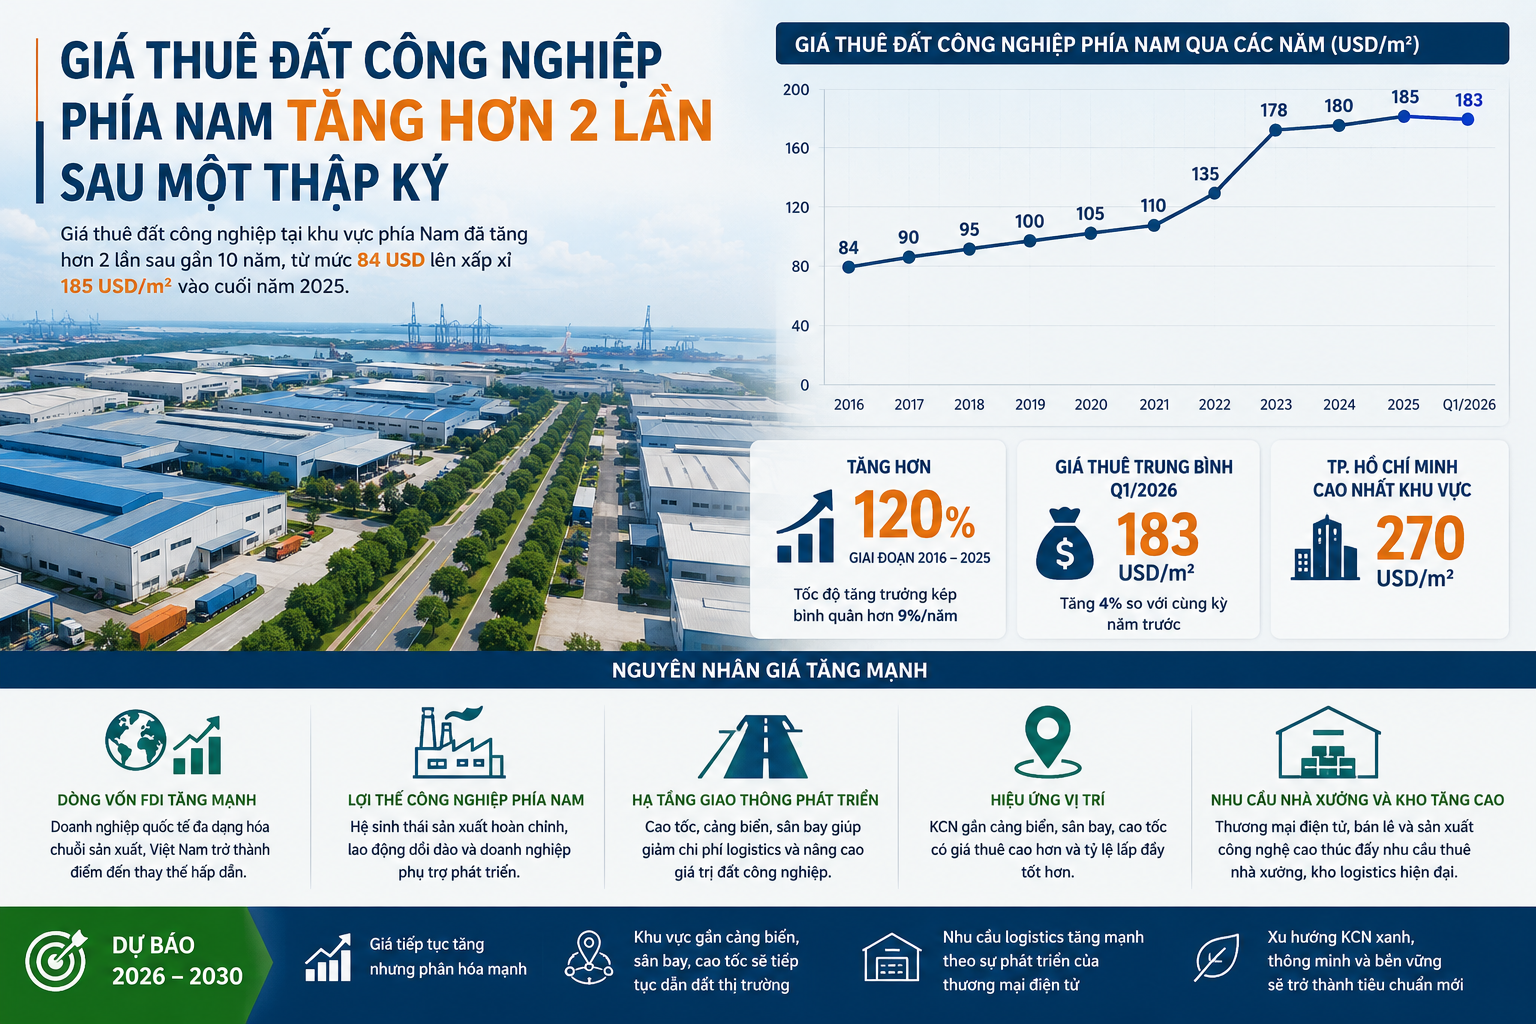
A Decade of Strong Growth in Industrial Real Estate
Over the past decade, industrial land rental prices in Southern Vietnam have experienced remarkable growth, becoming one of the most consistently appreciating segments in the country’s real estate market.
According to a report by Cushman & Wakefield, industrial land rents in the South increased by more than 120% between 2016 and 2025, rising from approximately USD 84/m² to nearly USD 185/m² for the full lease term.
👉 This represents a compound annual growth rate (CAGR) of over 9% per year, highlighting the region’s strong appeal to global manufacturing investments.
Industrial Land Price Trends by Period
2016–2019: Stable Growth
- 2016: ~USD 84/m²
- 2019: ~USD 100/m²
During this period, growth was driven by:
- Stable FDI inflows
- Competitive labor costs
- Vietnam’s deeper integration into global supply chains
2020–2021: Slower Growth Due to the Pandemic
- Prices ranged between USD 105–110/m²
Key factors included:
- Global trade disruptions
- Supply chain interruptions
- Slower investment activity
👉 Despite this, prices continued to rise slightly, reflecting the market’s resilience
2022–2025: Strong Acceleration
- 2022: ~USD 135/m²
- 2023: ~USD 178/m²
- 2024–2025: ~USD 180–185/m²
This period marked a major surge, driven by:
- Global manufacturers diversifying production
- Acceleration of the “China +1” strategy
- Vietnam emerging as a preferred alternative
👉 Notably, prices continued rising even as industrial land supply increased by over 80%
Early 2026: Growth Continues
According to CBRE Vietnam:
- Average asking rent: ~USD 183/m² (Q1/2026)
- Year-on-year increase: ~4%
Key highlights:
- Ho Chi Minh City: ~USD 270/m² (highest in the region)
- Dong Nai, Binh Duong: stable at high levels
👉 This indicates the market has not yet peaked
Key Drivers Behind Rising Industrial Land Prices
1. Strong Growth in FDI
The period from 2021–2023 marked a turning point as:
- Global companies diversified manufacturing locations
- Reduced reliance on a single country
👉 Vietnam stood out due to:
- Competitive costs
- Political stability
- Strategic location in Asia
2. Established Industrial Ecosystem in the South
Southern Vietnam is the country’s largest industrial hub, offering:
- Complete supply chains
- Abundant workforce
- Strong supporting industries
Leading provinces:
- Ho Chi Minh City
- Binh Duong
- Dong Nai
- Tay Ninh
👉 These areas maintain high occupancy rates and lead pricing trends
3. Rapid Infrastructure Development
Major infrastructure investments have played a key role:
- Expressways
- Ring roads
- Deep-sea ports
- Long Thanh International Airport
👉 Impact:
- Reduced logistics costs
- Faster transportation
- Increased land value
4. Location Advantage – A Key Pricing Factor
Industrial parks located:
- Near seaports
- Near airports
- Near major highways
👉 Typically have:
- Higher rental prices
- Better occupancy rates
Meanwhile:
- Remote or underdeveloped locations
👉 Must compete through pricing incentives
Not Only Land – Factories and Warehouses Are Also Increasing in Price
Rental Prices for Ready-Built Factories and Warehouses
According to CBRE:
- Factory: ~USD 5.2/m²/month
- Warehouse: ~USD 5.07/m²/month
👉 Increased by approximately 0.5% quarter-on-quarter
High Occupancy Rates
- Factories: ~93%
- Warehouses: ~80%
👉 Demonstrating strong real demand
Post-Pandemic Trends
Demand is rising from:
- E-commerce
- Retail
- High-tech manufacturing
👉 Tenants increasingly prefer:
- Ready-built factories
- Modern logistics facilities
- Operational-ready infrastructure
Market Shift: From Cost-Based to Value-Based Competition
Structural Transformation
After a decade, Southern Vietnam’s industrial real estate market has shifted from:
❌ Cost-driven advantages
- Cheap land
- Large land banks
➡️ To:
✅ Value-driven competitiveness
- Infrastructure quality
- Supply chain integration
- Operational efficiency
👉 Rental prices now reflect real industrial value
Market Outlook 2026–2030
1. Continued Growth with Stronger Differentiation
- High-quality industrial parks → price increases continue
- Lower-quality parks → compete on pricing
2. Key Growth Locations
Industrial parks near:
- Ports
- Airports
- Expressways
👉 Will continue to attract FDI
3. Rising Demand for Logistics
- E-commerce expansion
- Increasing domestic consumption
👉 Driving demand for:
- Warehousing
- Distribution centers
4. Shift Toward Green & Smart Industrial Parks
- ESG standards
- Carbon reduction
- Energy optimization
👉 Becoming essential requirements
Conclusion
The doubling of industrial land rental prices in Southern Vietnam over the past decade reflects not only strong demand but also a significant transformation of the market.
👉 From a cost-driven market, the region has evolved into:
- A manufacturing hub
- A logistics center
- A key destination for global FDI
In the medium term, Southern Vietnam’s industrial real estate sector still holds strong growth potential as the country continues to benefit from global supply chain shifts.
References:
Free access to exclusive information on warehouse, factory, and land rentals in Dong Nai, Binh Duong, Long An, Ho Chi Minh City, and more.
KHU CÔNG NGHIỆP 247 is a company operating in the field of buying, selling, and leasing factories and real estate.. We are proud to be a leading provider of real estate services in Vietnam. We have a team of highly qualified and experienced real estate consultants who always place trust and credibility at the core of everything we do.
Phone: 0901 490 348
Email: datkhucongnghiep247@gmail.com
Website: datkhucongnghiep247.com.vn