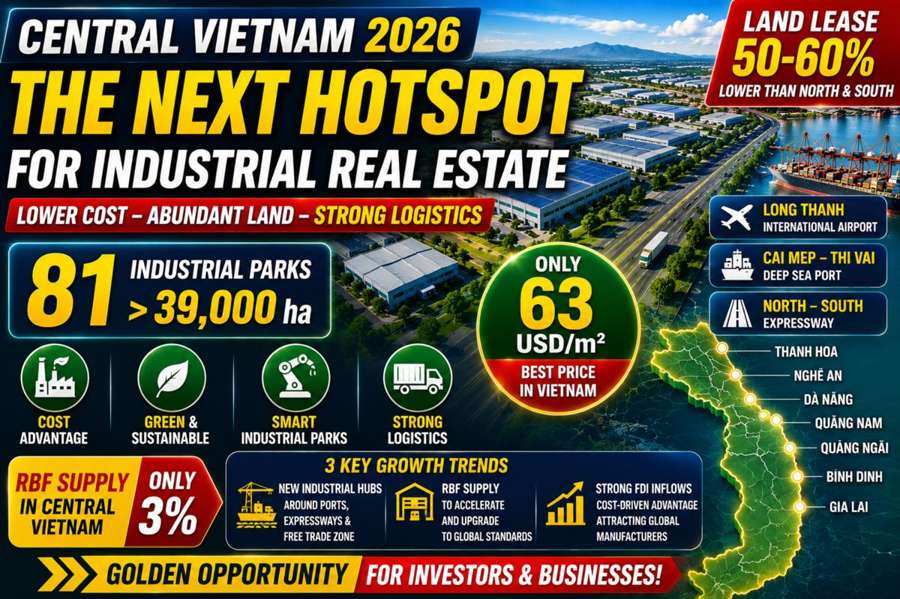
Overview of Central Vietnam’s Industrial Real Estate Market
As Vietnam’s industrial real estate enters a new growth cycle, Central Vietnam is emerging as a new investment hotspot. No longer overshadowed by the North and the South, this region is gradually positioning itself as the third major industrial growth pillar in the country.
According to market reports, Central Vietnam is attracting strong foreign direct investment (FDI) thanks to its competitive costs, abundant land supply, and improving logistics infrastructure. This not only helps reduce pressure on traditional industrial hubs but also opens up new opportunities for manufacturers and logistics companies.
👉 This is a pivotal period for Central Vietnam’s industrial real estate to accelerate growth from 2026 to 2030.
Competitive Advantages Driving FDI Inflows
Lower Industrial Land Rental Costs
One of the most significant advantages of Central Vietnam is its cost competitiveness.
- Average land lease price: ~63 USD/m² per lease term
- Northern Vietnam: ~143 USD/m²
- Southern Vietnam: ~185 USD/m²
👉 This is 50–60% lower, providing a major advantage for investors.
This is especially attractive for:
- Export-oriented businesses
- Large-scale manufacturing projects
- Cost-sensitive industries
Abundant Industrial Land Supply
Unlike the North and South, where land availability is becoming limited, Central Vietnam still offers:
- Large land reserves
- Flexible planning opportunities
- Competitive pricing
👉 This makes it ideal for long-term industrial investments.
Attractive Investment Policies
Local governments in Central Vietnam are actively promoting investment through:
- Corporate tax incentives
- Import tax exemptions for machinery
- Administrative reforms
👉 Creating a business environment that is:
✔ Transparent
✔ Efficient
✔ Investor-friendly
Regional Industrial Specialization
North Central Region – Electronics and Technology Hub
Provinces such as Thanh Hoa, Nghe An, and Ha Tinh are attracting:
- Electronics manufacturing
- Technology industries
- Light industries
👉 Key advantages:
- Skilled workforce
- Competitive labor costs
Central Coastal Region – Heavy Industry and Manufacturing
Da Nang, Quang Nam, and Quang Ngai focus on:
- Automotive manufacturing (THACO)
- Mechanical engineering
- Steel production (Dung Quat)
👉 A strong foundation for large-scale industrial development
South Central Region – Processing and Manufacturing
Binh Dinh and Gia Lai are developing:
- Furniture manufacturing
- Wood processing
- Supporting industries
👉 Leveraging raw material supply from the Central Highlands
Ready-Built Factory (RBF) Segment: High Potential
Limited Supply – Huge Opportunity
Current RBF market share:
- Southern Vietnam: ~59%
- Northern Vietnam: ~38%
- Central Vietnam: only ~3%
👉 This indicates a massive growth opportunity for investors.
Upgrading Industrial Standards
While the North and South have already adopted:
- Multi-story factories
- ESG-certified facilities
- Smart infrastructure
Central Vietnam still mainly offers:
- Traditional single-story factories
- Basic infrastructure
👉 This creates strong potential for:
✔ Modern warehouse development
✔ High-quality tenant attraction
✔ Rental value growth
3 Key Trends Shaping Central Vietnam Industrial Real Estate
1. New Industrial Hubs Driven by Infrastructure
New industrial zones are forming around:
- Seaports (Lien Chieu, Dung Quat)
- North–South Expressway
- Da Nang Free Trade Zone (~1,800 ha)
👉 Creating strong logistics advantages
2. Rapid Growth of High-Quality Factory Supply
Driven by demand from:
- Electronics
- High-tech industries
- Semiconductor sector
👉 The market will:
- Increase RBF supply
- Improve technical standards
- Catch up with Hanoi and Ho Chi Minh City
3. Three Strategic Industrial Regions
- Southern Vietnam: Market-driven
- Northern Vietnam: Technology-driven
- Central Vietnam: Cost-driven
👉 This defines Vietnam’s new industrial structure
The Role of Logistics Infrastructure
Infrastructure is the biggest growth driver in Central Vietnam:
- Lien Chieu Port
- North–South Expressway
- Coastal transport routes
- Free Trade Zones
👉 Benefits include:
✔ Reduced logistics costs
✔ Faster delivery times
✔ Improved supply chain efficiency
Opportunities for Investors and Businesses
For Investors
- Acquire industrial land at competitive prices
- Develop ready-built factories
- Capture early FDI inflows
For Tenants
- Lower rental costs
- Flexible expansion options
- Improving infrastructure
For Logistics Companies
- Develop distribution centers
- Cold storage facilities
- Regional logistics hubs
Conclusion
Central Vietnam’s industrial real estate market is entering a new phase with strong advantages:
✔ Competitive costs
✔ Large land availability
✔ Rapidly improving infrastructure
✔ Attractive investment policies
👉 From 2026–2030, the region is expected to become:
- A strategic FDI destination
- A new industrial hub of Vietnam
- A high-potential market for factory and warehouse leasing
➡️ This is the golden window for investors and businesses to capitalize on emerging opportunities.
References:
Free access to exclusive information on warehouse, factory, and land rentals in Dong Nai, Binh Duong, Long An, Ho Chi Minh City, and more.
KHU CÔNG NGHIỆP 247 is a company operating in the field of buying, selling, and leasing factories and real estate.. We are proud to be a leading provider of real estate services in Vietnam. We have a team of highly qualified and experienced real estate consultants who always place trust and credibility at the core of everything we do.
Phone: 0901 490 348
Email: datkhucongnghiep247@gmail.com
Website: datkhucongnghiep247.com.vn